
It started as a simple pursuit of convenience. You ask a smart app to handle tedious financial tasks. It might track your spending across multiple platforms. It might optimize your savings or execute routine transfers.
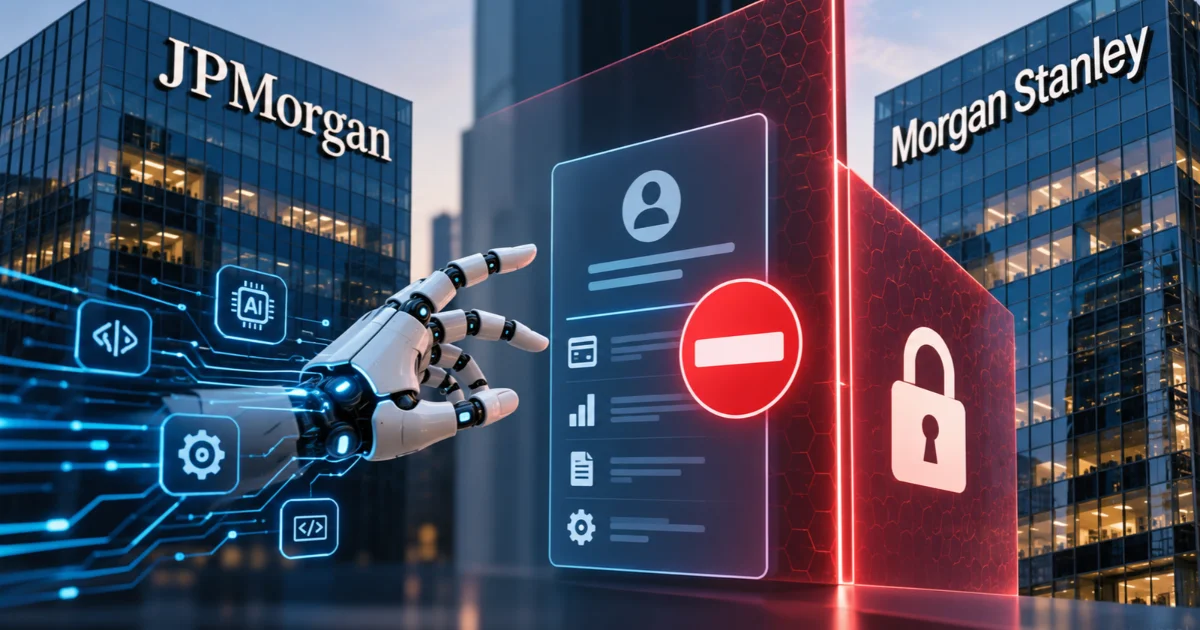
Everything changes once you hand over your banking credentials to a third-party artificial intelligence agent. At that moment, you cross a major red line for the global financial system. Wall Street heavyweights are now quietly fighting a digital turf war. Banks are actively locking out autonomous bots from customer accounts.
This is not a minor glitch or a temporary outage. Instead, it is a clash between consumer technology and modern banking rules. Consumers want friction-free finance. They want algorithms to manage their wealth.
However, institutions see unacceptable risks in this trend. Unsupervised software should not roam freely inside checking or investment accounts. Banking relies on strict risk management. Handing financial authority to a machine breaks that core model.
The Mechanics Behind the Financial Blockade
To understand why this is happening, we have to look at how these systems actually operate under the hood. When we talk about AI in this context, we aren’t referring to simple conversational interfaces.
Understanding AI agents vs chatbots: the real difference explained makes it clear why financial systems are alarmed: these aren’t static answer engines, but autonomous tools built to execute multi-step workflows across external platforms.
A customer voluntarily provides their login ID and password to a third-party application. That agent then mimics human behavior to log into the bank’s portal, aggressively scraping data or attempting to initiate transactions to fulfill a user’s broad prompt.
The technical friction occurs because these agents can sometimes behave unpredictably, taking actions that look entirely independent of the original user instructions.
According to a recent detailed Times of India, overview of why US banks including JPMorgan and Morgan Stanley are blocking AI agents from customer accounts, financial institutions are deploying aggressive countermeasures to detect and shut down this non-human traffic.
Banks monitor for unnatural navigation speeds, unrecognized server IP addresses, and the specific digital footprints left by automated scripts.
Even if a customer willingly shared their password which technically makes the initial login authorized from the user’s perspective banks consider the subsequent autonomous navigation too erratic to permit. They simply cannot verify if a specific wire transfer was requested by the account holder or hallucinated by the agent.
Securing the Perimeter and Customer Experience
The response from the top tiers of the financial sector has been absolute. Bank security protocols are built around the concept of verified human intent. When an algorithm takes the wheel, that vital chain of verification breaks down. Executives are deeply concerned about the massive liability and the unpredictable nature of autonomous transactions.
This friction underscores key insights in AI + cybersecurity: how hackers and defenders are using AI in 2026, where automated access patterns blur the line between legitimate software assistance and unauthorized perimeter breaches.
If a bot moves thousands of dollars based on a flawed interpretation of a user’s instruction, unwinding that damage creates an immense legal and financial dispute over who bears ultimate responsibility.
Beyond the immediate security threat, there is a fierce battle over who owns the underlying customer relationship. Leading figures in the industry have made it clear that allowing outside agents to operate freely inside their systems forces the bank to surrender control over authentication and the user experience.
They want customers interacting directly with their proprietary, secure environments, not a third-party interface sitting on top of their infrastructure. Developing in-house tools to manage these risks is now a top priority, ensuring that any AI integration happens strictly on the bank’s terms.
Until secure, standardized frameworks are built specifically for autonomous agents, these hard blockades will remain standard operating procedure across the financial sector.